AI That Shows Up in the P&L Before You Sell
Buyers are tired of AI theater. A slide that says the company is “AI enabled” does almost nothing in diligence. What does move value is AI that shows up in the P&L before you sell: lower labor cost per unit, faster cycle times, fewer write-offs, better win rates, or measurable gross margin lift that you can defend with operating data. For a related take on personal AI assistants versus desktop agents, see our Muse vs Instinct vs OpenAI Dot comparison.
If you are preparing a sale in the next 12 to 24 months, the goal is not to sound modern. The goal is to put durable operating improvement into the financials so a sell-side diligence lens can see it without storytelling gymnastics.
AI theater versus AI that earnings can prove
AI theater looks familiar. A chatbot on the website. A pilot with no owner. A vendor dashboard nobody opens in the weekly meeting. A paragraph in the CIM about innovation culture. None of that survives a thoughtful buyer asking for the before-and-after metrics.
AI that shows up in the P&L has a different shape. It is tied to a process, a cost line, a throughput measure, or a revenue conversion rate. Someone owns the KPI. The change has been live long enough to show a trend, not a weekend demo. When diligence asks “so what?”, you can answer with dollars, hours, scrap rates, or booking conversion, not with model names.
Where measurable ops outcomes usually appear
Lower middle market companies rarely need frontier research models. They need applied tools that remove friction from work that already exists. The highest-confidence outcomes we see in sell-side prep tend to cluster in a few places.
Cost to serve and labor productivity
Quote generation, estimating, scheduling, invoice chasing, and exception handling eat manager time. When AI assists those workflows and the company tracks hours per job or revenue per employee, the P&L impact is straightforward. Buyers like that because they can underwrite continuity after closing if the process is documented.
Inventory, waste, and quality
Demand sensing, anomaly detection on scrap, and better exception alerts can reduce write-offs and overtime. The proof is not the algorithm. The proof is a lower variance in COGS, fewer rush shipments, or a cleaner aging inventory report over several months.
Revenue operations that convert
Lead scoring, proposal drafting, and renewal risk alerts only matter if win rate, cycle time, or retention moves. If your CRM still cannot show a clean funnel, AI will not invent credibility. Fix the pipeline truth first, then automate the parts that already have a baseline.
Customer support load
Deflection only counts when ticket volume, handle time, or CSAT moves without hiding unresolved issues. Buyers will poke at whether savings came from better service design or from starving the customer. Bring both the cost line and the quality metric.
The sell-side diligence lens buyers actually use
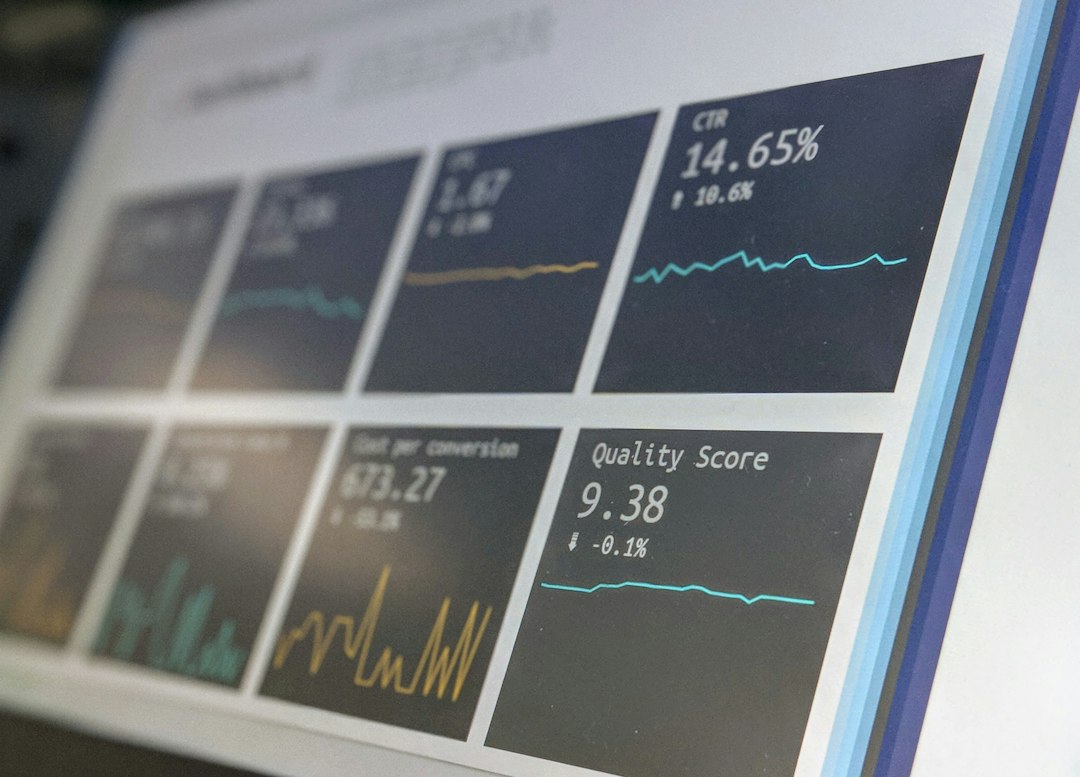
When a serious buyer evaluates AI claims, they run a simple diligence lens. You should run it on yourself before the CIM goes out.
- Baseline: What was the KPI for the 6 to 12 months before the tool went live?
- Change: What changed in the process, who owns it, and what still depends on one person?
- Evidence: Can you show system exports, not screenshots from a vendor deck?
- Durability: Does the improvement hold when volume spikes or a key employee is out?
- Transfer: Can a new owner keep the result without the founder as the prompt engineer?
If you cannot clear those five points, keep the AI story out of the valuation narrative. Put it in a future opportunity section if you must. Do not ask a buyer to pay a multiple on an unproven pilot.
How to get AI into the P&L before you sell
Owners often ask how long they need. The honest answer is that one clean quarter is better than twelve noisy demos, and three to four quarters of sustained improvement is what supports a stronger earnings claim. Start with one workflow tied to a material cost or revenue line. Instrument it. Assign an owner. Review it in the same meeting where you review cash and backlog.
Then document the bridge. Show reported results, the operating KPI movement, and how that maps to adjusted earnings. If the savings freed capacity that you redeployed into growth, say so clearly. Buyers distrust silent headcount cuts that rebound after closing. They respect capacity that was redirected with evidence.
What not to do in the CIM
Do not lead with model vendors. Do not claim “AI-driven moat” without switching costs or proprietary data. Do not bury a thin pilot next to core earnings as if they are the same quality. And do not wait until management meetings to invent the KPI story. Diligence teams compare notes. Inconsistency reads as theater.
Also avoid treating AI as a substitute for basic financial hygiene. If your books, customer files, and CURRENT pack are messy, no dashboard will save the process. Clean memory first. Then automate. Then sell the result that landed in the P&L.
How Icon coaches sell-side AI claims
Icon helps owners separate measurable operating improvement from marketing language before buyers do it for them. We look at the KPI trail, the P&L bridge, and the transfer story so the CIM only asks for credit the diligence can support. That keeps valuation conversations grounded and protects credibility when a buyer brings their own ops diligence team.
If you want AI to help your sale, make it boring in the best way: visible in the numbers, owned by a process, and ready for a buyer to keep after closing. Theater gets polite nods. Proven ops outcomes get paid for.
Related reading: Muse vs Instinct vs OpenAI Dot, fix memory before you automate, and the CURRENT pack.
Want your AI story to survive diligence?
Icon Business Advisors helps sellers turn operating improvements into a P&L story buyers can underwrite. Call (615) 931-0001 or schedule a conversation.